
Research Paper:
Asymmetric Multifractal Risks in Green Finance Markets
Xiaoyang Zhuang†

Institute for Quantitative Economics and Statistics, Huaqiao University
No.668 Jimei Avenue, Jimei District, Xiamen 361021, China
†Corresponding author

This study investigates asymmetric multifractal characteristics and nonlinear risk dynamics of different China’s green finance markets. By asymmetric multifractal detrended fluctuation analysis, this paper examines scaling behaviors and informational efficiency across varying time scales. The empirical results confirm significant long-range dependence in all examined indices, exhibiting highly asymmetric multifractality. Further analysis of asymmetric singularity spectrum uncovers distinct risk structures among green indices. An analysis of time-varying feature of multifractality, long-range memory, and market inefficiency reveals distinct scaling asymmetries, which manifest as locally stable multifractality and pronounced regime-switching driven by policies, crises, and market mechanism. By revealing the dynamics, this research provides critical insights for investors and policymakers in developing robust green hedging strategies.
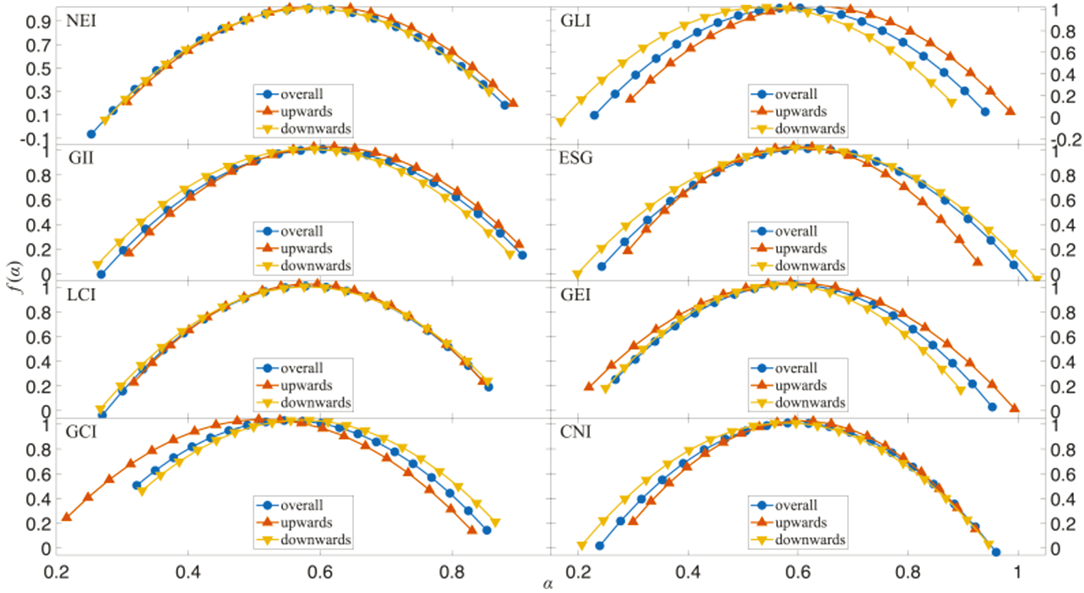
Asymmetric multifractal spectra
- [1] X. Fan, X. Lv, J. Yin et al., “Multifractality and market efficiency of carbon emission trading market: Analysis using the multifractal detrended fluctuation technique,” Applied Energy, Vol.251, Article No.113333, 2019. https://doi.org/10.1016/j.apenergy.2019.113333
- [2] S. Arshad, S. A. R. Rizvi, O. Haroon et al., “Are oil prices efficient?,” Economic Modelling, Vol.96, pp. 362-370, 2021. https://doi.org/10.1016/j.econmod.2020.03.018
- [3] J. Alvarez-Ramirez, M. Cisneros, C. Ibarra-Valdez et al., “Multifractal Hurst analysis of crude oil prices,” Physica A: Statistical Mechanics and its Applications, Vol.313, Nos.3-4, pp. 651-670, 2002. https://doi.org/10.1016/S0378-4371(02)00985-8
- [4] X. Zhuang, Y. Wei, and F. Ma, “Multifractality, efficiency analysis of Chinese stock market and its cross-correlation with WTI crude oil price,” Physica A: Statistical Mechanics and its Applications, Vol.430, pp. 101-113, 2015. https://doi.org/10.1016/j.physa.2015.02.085
- [5] A. K. Tiwari, S. Kumar, R. Pathak et al., “Testing the oil price efficiency using various measures of long-range dependence,” Energy Economics, Vol.84, Article No.104547, 2019. https://doi.org/10.1016/j.eneco.2019.104547
- [6] L. H. S. Fernandes, F. H. A. de Araújo, and I. E. M. Silva, “The (in)efficiency of NYMEX energy futures: A multifractal analysis,” Physica A: Statistical Mechanics and its Applications, Vol.556, Article No.124783, 2020. https://doi.org/10.1016/j.physa.2020.124783
- [7] W. Mensi, A. K. Tiwari, and K. H. Al-Yahyaee, “An analysis of the weak form efficiency, multifractality and long memory of global, regional and European stock markets,” The Quarterly Review of Economics and Finance, Vol.72, pp. 168-177, 2019. https://doi.org/10.1016/j.qref.2018.12.001
- [8] S. Ali, S. J. H. Shahzad, N. Raza et al., “Stock market efficiency: A comparative analysis of Islamic and conventional stock markets,” Physica A: Statistical Mechanics and its Applications, Vol.503, pp. 139-153, 2018. https://doi.org/10.1016/j.physa.2018.02.169
- [9] K. H. Al-Yahyaee, W. Mensi, and S.-M. Yoon, “Efficiency, multifractality, and the long-memory property of the Bitcoin market: A comparative analysis with stock, currency, and gold markets,” Finance Research Letters, Vol.27, pp. 228-234, 2018. https://doi.org/10.1016/j.frl.2018.03.017
- [10] G. Cao, J. Cao, and L. Xu, “Asymmetric multifractal scaling behavior in the Chinese stock market: Based on asymmetric MF-DFA,” Physica A: Statistical Mechanics and its Applications, Vol.392, No.4, pp. 797-807, 2013. https://doi.org/10.1016/j.physa.2012.10.042
- [11] A. Khurshid, K. Khan, J. Cifuentes-Faura et al., “Asymmetric multifractality: Comparative efficiency analysis of global technological and renewable energy prices using MFDFA and A-MFDFA approaches,” Energy, Vol.289, Article No.130106, 2024. https://doi.org/10.1016/j.energy.2023.130106
- [12] G. Cao and L. Zhou, “Asymmetric risk transmission effect of cross-listing stocks between mainland and Hong Kong stock markets based on MF-DCCA method,” Physica A: Statistical Mechanics and its Applications, Vol.526, Article No.120741, 2019. https://doi.org/10.1016/j.physa.2019.03.106
- [13] M. A. F. Chowdhury, M. Abdullah, M. Alam et al., “NFTs, DeFi, and other assets efficiency and volatility dynamics: An asymmetric multifractality analysis,” Int. Review of Financial Analysis, Vol.87, Article No.102642, 2023. https://doi.org/10.1016/j.irfa.2023.102642
- [14] M. Lee, J. W. Song, J. H. Park et al., “Asymmetric multi-fractality in the U.S. stock indices using index-based model of A-MFDFA,” Chaos, Solitons & Fractals, Vol.97, pp. 28-38, 2017. https://doi.org/10.1016/j.chaos.2017.02.001
- [15] M. Lee, J.-W. Song, J.-H. Park, and W. Chang, “Asymmetric multi-fractality in the U.S. stock indices using index-based model of A-MFDFA,” Chaos, Solitons & Fractals, Vol.97, pp. 28-38, 2017. https://doi.org/10.1016/j.chaos.2017.02.001
- [16] X. Zhuang and D. Wei, “Asymmetric multifractality, comparative efficiency analysis of green finance markets: A dynamic study by index-based model,” Physica A: Statistical Mechanics and its Applications, Vol.604, Article No.127949, 2022. https://doi.org/10.1016/j.physa.2022.127949
- [17] K. Khan, C.-W. Su, A. Khurshid et al., “COVID-19 impact on multifractality of energy prices: Asymmetric multifractality analysis,” Energy, Vol.256, Article No.124607, 2022. https://doi.org/10.1016/j.energy.2022.124607
- [18] W. Mensi, A. Sensoy, X. V. Vo et al., “Pricing efficiency and asymmetric multifractality of major asset classes before and during COVID-19 crisis,” The North American J. of Economics and Finance, Vol.62, Article No.101773, 2022. https://doi.org/10.1016/j.najef.2022.101773
- [19] T. Takaishi, “Time-varying properties of asymmetric volatility and multifractality in Bitcoin,” PLOS ONE, Vol.16, No.2, Article No.e0246209, 2021. https://doi.org/10.1371/journal.pone.0246209
- [20] P. Cho and M. Lee, “Forecasting the Volatility of the Stock Index with Deep Learning Using Asymmetric Hurst Exponents,” Fractal and Fractional, Vol.6, No.7, Article No.394, 2022. https://doi.org/10.3390/fractalfract6070394
This article is published under a Creative Commons Attribution-NoDerivatives 4.0 Internationa License.